

The rapid acceleration of the digital economy, fueled by the proliferation of artificial intelligence and cloud computing, has created a widening rift between the pace of technological infrastructure development and the operational capacity of the American electrical grid. While a modern data center can be constructed in approximately 18 to 24 months, the timeline for securing a reliable high-voltage connection to the power grid has ballooned to nearly five years. This discrepancy, highlighted by recent findings from the Lawrence Berkeley National Laboratory, underscores a systemic crisis: the traditional utility business model, designed for a slower era of centralized generation, is failing to keep pace with the urgent demands of the "Great Transformation."
This disconnect reached a critical juncture in the summer of 2026. In July, PJM Interconnection, which manages the largest power grid in the United States, proposed a controversial set of new regulations. These rules would grant the grid operator the authority to temporarily curtail power to data centers during periods of peak demand or supply shortages. This "backstop" measure serves as an alternative to the massive, multi-year capital investments required to build out the supply infrastructure necessary to meet every potential consumption spike. Simultaneously, the private sector has begun to bypass traditional utility constraints. In June 2026, Google announced a landmark agreement to fund a 100-megawatt "virtual power plant" (VPP) in partnership with Voltus. This software-driven initiative bundles thousands of decentralized assets—such as residential batteries and smart thermostats—into a singular, flexible resource that can sell energy back to the grid, mimicking the output of a traditional large-scale power station.
The Structural Impasse: Understanding the Utility Rate Base Model
To understand why the integration of data centers and renewable energy is stalling, one must examine the financial incentives governing investor-owned utilities (IOUs). For decades, the primary mechanism for utility profit has been the "rate base" model. Under this system, utilities earn a return on investment—typically targeted at approximately 10%—based on the value of the physical assets they own and operate. These assets include coal and gas plants, substations, and thousands of miles of transmission lines.

From a corporate perspective, every dollar spent on building and owning new, large-scale infrastructure increases the rate base, thereby securing long-term returns for shareholders. Conversely, operating costs are treated differently. When a utility implements efficiency measures or runs under budget, it may retain the savings until its next regulatory rate case. However, purchasing capacity from a third-party provider—such as a distributed energy resource (DER) owned by a homeowner or a private tech firm—is categorized as a cost rather than a capital investment. Because this expenditure does not add to the rate base, it offers no lasting financial return to the utility’s investors.
This structural reality creates a perverse incentive. Utilities are financially encouraged to favor slow, centrally owned infrastructure projects over the immediate integration of ready-to-use, independent energy resources. This "CAPEX vs. OPEX" conflict is the primary reason why distributed energy has historically been relegated to a secondary role, often viewed as a backup system rather than a core component of the national energy strategy.
The Great Transformation: Insights from the Bend Summit
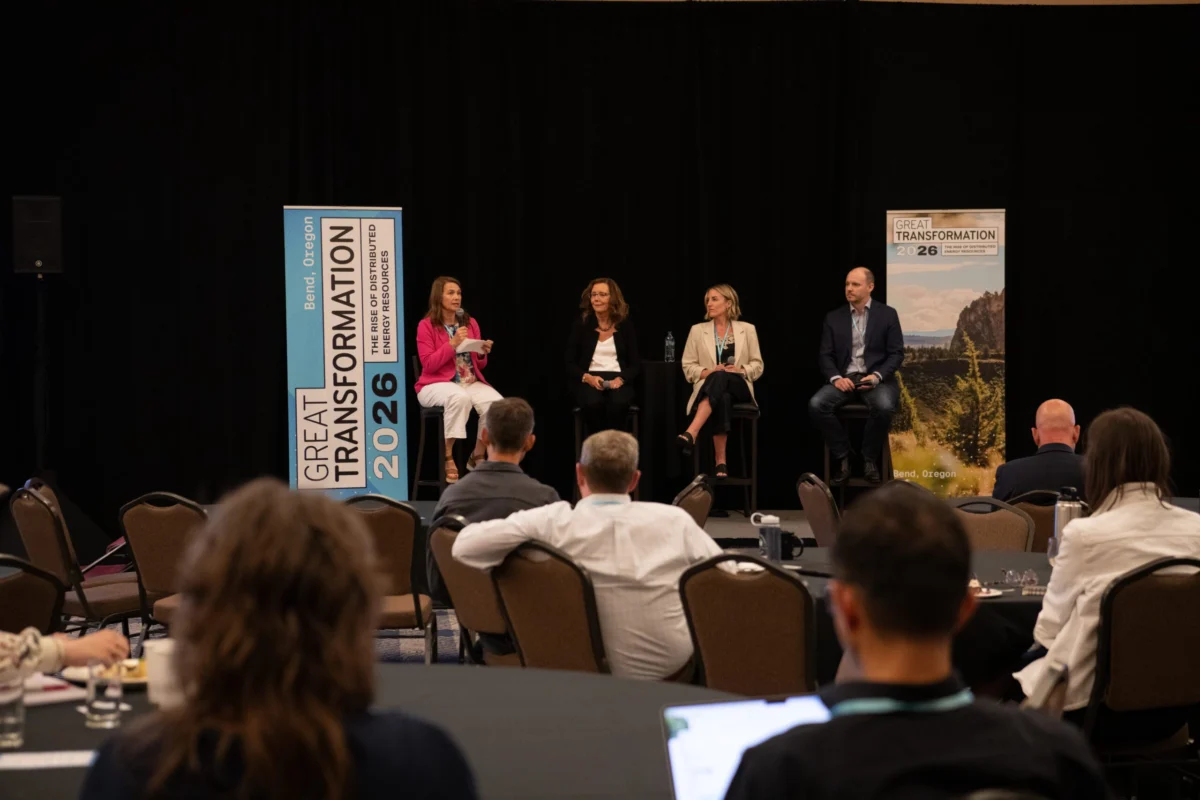
The urgency of this crisis was the focal point of the "Great Transformation" summit held in Bend, Oregon, in late 2026. The event convened a diverse coalition of utility executives from organizations such as Portland General Electric and Puget Sound Energy, alongside grid operators, technology leaders from Amazon Web Services, and policymakers. The consensus among participants was clear: the survival of the grid depends on the aggressive expansion of Distributed Energy Resources.
DERs represent a shift toward "behind-the-meter" generation. This includes rooftop solar arrays, industrial-scale battery storage, and localized microgrids that produce electricity where it is consumed, rather than relying on the fragile and congested long-distance transmission network. In the Pacific Northwest, where the threat of wildfires has become a seasonal reality, these systems provide more than just power; they offer "affordable resilience." When utilities are forced to execute Public Safety Power Shutoffs (PSPS) to prevent electrical equipment from sparking fires, facilities equipped with independent storage and generation can continue to operate, mitigating the economic impact of grid instability.

The Chronology of Grid Reform and the Rise of the Prosumer
The path toward a modernized grid has been marked by several key regulatory and technological milestones over the past two decades:
- 2008: Interconnection wait times for new generation projects were significantly shorter, often averaging less than two years. The grid was primarily dealing with predictable, centralized power plants.
- 2020: The Federal Energy Regulatory Commission (FERC) issued Order No. 2222. This landmark ruling mandated that regional grid operators allow aggregated DERs to participate in wholesale power markets. It effectively laid the legal groundwork for virtual power plants.
- 2025: Utah became a pioneer in consumer energy autonomy by legalizing "plug-in balcony solar" systems. This allowed renters and homeowners to generate their own power without complex permanent installations.
- Early 2026: Nine additional states, including California, followed Utah’s lead, officially legalizing balcony solar and opening a massive new market for consumer-level energy technology.
- June 2026: Google’s 100-MW VPP deal demonstrated the commercial viability of using software to manage grid demand, signaling a shift in how tech giants view their role as energy consumers and producers.
- July 2026: PJM’s curtailment proposal highlighted the physical limits of the existing grid and the desperate need for flexible load management.
These events illustrate a broader trend: the rise of the "prosumer"—a consumer who also produces energy. The instinct to distrust large, slow-moving institutions has driven individuals and corporations alike to seek greater control over their energy reliability. The fact that citizens are willing to pay for their own solar and storage solutions indicates a market ready for transition, provided the regulatory framework can catch up.
Regional Challenges and the Role of Data Centers
Data centers are often criticized as "power-hungry" entities that strain local resources. However, industry experts at the Bend summit argued that data centers can actually serve as catalysts for grid modernization. Because data center operators—such as Google, Microsoft, and Amazon—have aggressive carbon-neutrality goals, they are the primary drivers of demand for renewable energy and advanced storage solutions.
In Oregon and Washington, utilities like Portland General Electric (PGE) are working to integrate these large loads without passing excessive costs to residential consumers. The challenge lies in "decoupling" utility profits from the sheer volume of infrastructure built. If regulators can create pathways for utilities to earn a return on "grid orchestration"—the management of third-party DERs and VPPs—the incentive to delay interconnection would vanish.

Furthermore, the integration of AI into grid management is becoming a necessity. Managing a grid with millions of small, fluctuating energy sources (like solar panels and EV batteries) is humanly impossible. It requires real-time, AI-driven software to balance supply and demand. In this sense, the very data centers that are straining the grid may provide the computational power needed to save it.
Broader Implications and the Path Forward
The transition to a decentralized grid is no longer a matter of environmental preference; it is a matter of economic and national security. The current five-year wait for grid connection is a bottleneck that threatens American leadership in the AI revolution. If the U.S. cannot power its data centers, the infrastructure—and the innovation that comes with it—will move elsewhere.
To bridge the gap, three primary reforms are necessary:
- Regulatory Reform of the Rate Base: State utility commissions must modernize how IOUs earn profits. Incentives should be tied to performance metrics, such as grid reliability and the successful integration of third-party DERs, rather than just the ownership of physical hardware.
- Standardization of Price Signals: For virtual power plants to flourish, there must be clear, transparent pricing for the value that distributed energy provides to the grid. A battery sitting idle is a wasted asset; a battery enrolled in a VPP that earns revenue for every hour of availability is a powerful economic tool.
- Streamlining Interconnection: Federal and state agencies must collaborate to reduce the administrative hurdles for new connections. This includes adopting "surplus interconnection" rules that allow new resources to use existing, underutilized connection points.
The lesson from the "Great Transformation" in Bend is that the technology to solve the energy crisis already exists. The hardware is ready, and the private sector is willing to invest. The remaining obstacles are structural and political. As the energy transition continues, the regions and businesses that successfully rethink the relationship between utilities and customers will emerge as the leaders of the new digital economy. The era of the passive ratepayer is ending; the era of the active, resilient energy participant has begun.
