

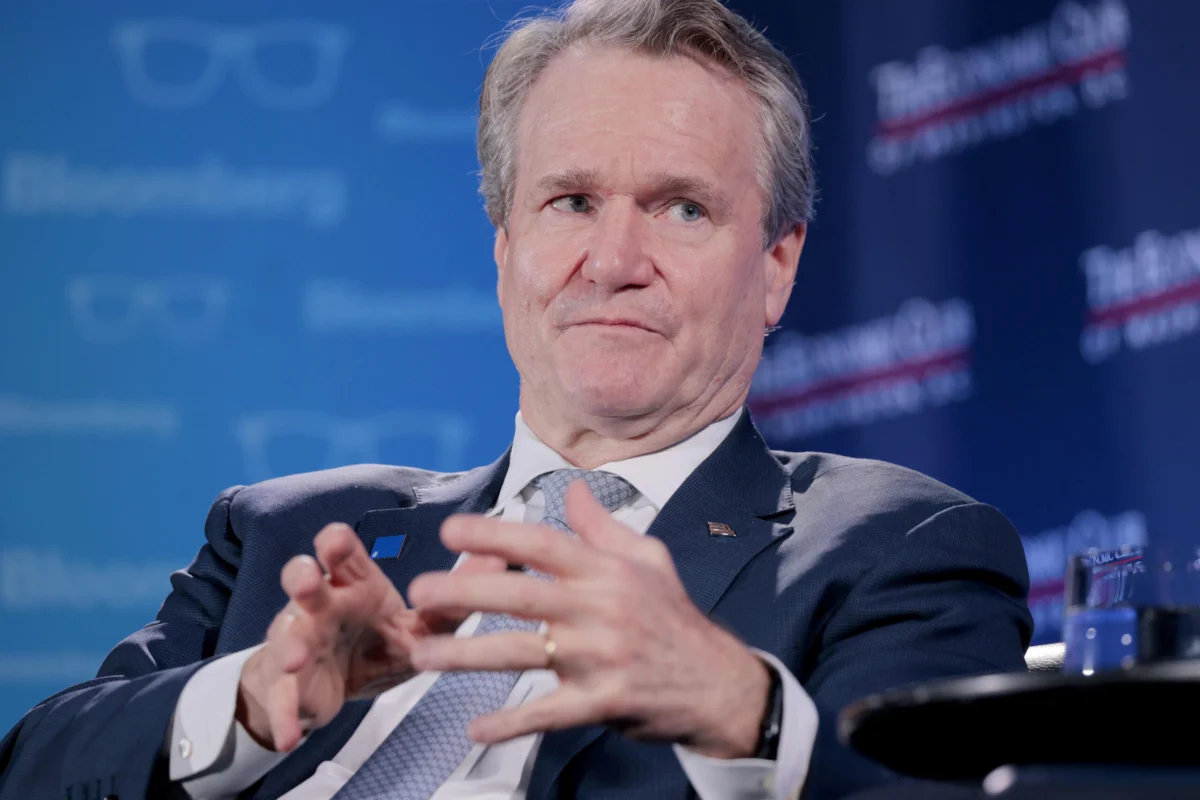
Bank of America experienced a substantial decline in its third-quarter profitability, reporting a 17% drop to $6.93 billion, or 91 cents per share, as the financial giant absorbed a significant $1.2 billion penalty from U.S. regulators. This regulatory hit, which alone shaved 17 cents off the earnings per share, coincided with a revenue shortfall that largely stemmed from weaker-than-anticipated performance in its critical trading operations, missing expectations by approximately $750 million. The confluence of these factors sent Bank of America’s shares tumbling by almost 5% on Wednesday, signaling investor apprehension regarding the bank’s operational controls and market-facing divisions.
The financial institution’s company-wide revenue for the quarter rose by a modest 3.2% to $30.12 billion on a full-time equivalent (FTE) basis. However, this figure fell short of LSEG (formerly Refinitiv) estimates of $30.69 billion and StreetAccount estimates by about $570 million, primarily due to the underperformance within its Wall Street trading desks. This disappointment was particularly acute in fixed income trading, where revenue plummeted by 17% to $2.55 billion. This sharp decline was attributed to prevailing weaknesses across mortgage, municipal, and credit activity, missing the StreetAccount estimate by roughly $450 million. While equities trading revenue saw a 10% increase to $2.51 billion, it too failed to meet analysts’ expectations, coming in nearly $300 million below projections. The combined bond and stock trading results ultimately declined by 5%, directly contradicting CEO Brian Moynihan’s earlier guidance to analysts last month that trading revenue would remain "roughly flat."
Investment banking revenue also faced headwinds, falling 11% to $1.8 billion, though this figure was largely in line with both market expectations and Moynihan’s September guidance. A silver lining for Bank of America came from its net interest income (NII), a crucial profitability driver for the bank, which surged by 7.9% to $16.6 billion, slightly surpassing the StreetAccount estimate of $16.53 billion. The robust NII performance reflects the benefit of higher interest rates on the bank’s lending activities, partially offsetting some of the other financial pressures.
The Weight of Regulatory Scrutiny and the $1.2 Billion Penalty
The most significant immediate impact on Bank of America’s third-quarter results was the hefty $1.2 billion penalty imposed by U.S. regulators. This substantial fine, announced on Tuesday, just ahead of the earnings release, added an eleventh-hour layer of complexity to what was otherwise shaping up to be a challenging but routine bank earnings week. The "Treasury episode," as it was referred to, specifically highlighted the company’s failure to report billions of dollars in suspicious transactions, as articulated by the U.S. Treasury Department’s Financial Crimes Enforcement Network (FinCEN) and potentially other agencies such as the Office of the Comptroller of the Currency (OCC) or the Federal Reserve.
This regulatory action underscores the increasing intensity of oversight on financial institutions regarding compliance with the Bank Secrecy Act (BSA) and Anti-Money Laundering (AML) regulations. The BSA, a cornerstone of U.S. financial crime prevention, requires banks to assist government agencies in detecting and preventing money laundering by reporting suspicious activities and maintaining specific records. Failures to adhere to these stringent requirements can result in severe penalties, as Bank of America has now experienced. The fine raises critical questions about the robustness of Bank of America’s internal controls and compliance infrastructure, especially concerning its ability to monitor and report potentially illicit financial flows effectively.
For CEO Brian Moynihan, who assumed leadership in 2010, this fine brings a renewed focus on internal governance. Early in his tenure, Moynihan dedicated considerable effort to remediating the widespread mortgage-related abuses that plagued the bank in the aftermath of the 2008 financial crisis. The current penalty, related to fundamental compliance failures, suggests that despite previous efforts to strengthen controls, significant gaps or breakdowns persisted within the bank’s operational framework. This regulatory setback not only imposes a direct financial cost but also carries substantial reputational implications, potentially eroding investor confidence and raising concerns among clients about the bank’s operational integrity.
Analyst Scrutiny and Management’s Defense
The earnings call on Wednesday saw analysts pressing Bank of America’s management on various fronts, particularly the sharp decline in share price and the unexpected regulatory charge. Wells Fargo analyst Mike Mayo minced no words, labeling the firm’s capital markets results as "easily worst in class" for the quarter. This pointed criticism highlights Bank of America’s underperformance compared to its peers in a crucial revenue-generating segment, suggesting potential structural or strategic issues that need addressing.
JPMorgan analyst Vivek Juneja echoed broader market concerns, remarking on the magnitude of the charge. "Clearly you’ve had a huge charge this morning," Juneja stated, acknowledging that while the bank could absorb a billion-dollar penalty, "it’s a reputational and confidence issue." This sentiment underscores that the damage extends beyond the balance sheet, affecting the bank’s standing in the market and its relationship with investors. Analysts also questioned management on the pace of future share repurchases, a key mechanism for returning capital to shareholders, and sought detailed explanations for the bank’s trading underperformance.

In response to the trading disappointment, particularly in fixed income, CFO Alastair Borthwick attributed the results to the prevailing market conditions. He explained that a sharp increase of 85 basis points in interest rates during the quarter "tends not to be good for" credit and mortgage trading businesses. Rapid shifts in interest rates can lead to significant volatility in bond prices, affecting the valuation of existing fixed income portfolios and creating challenging trading environments, especially for market-making activities in less liquid segments like municipals and certain credit products. This explanation, while offering context, did not fully assuage concerns about the magnitude of Bank of America’s underperformance relative to some of its competitors who managed the rate environment more effectively.
Leadership’s Assurance Amidst Lingering Questions
Later on Wednesday, in an interview with CNBC’s Leslie Picker, CEO Brian Moynihan addressed the ongoing regulatory issues, albeit without committing to a specific timeline for their resolution. "We got to do the work, and then the regulators look at it," Moynihan stated, emphasizing the iterative nature of compliance remediation. He added, "So I don’t want to speculate about the precise timeline." Despite the lack of a definitive timeline, the CEO expressed confidence in the bank’s direction: "confident that we are on the right course to remediate everything."
Moynihan’s statement reflects a recognition of the significant undertaking required to satisfy regulatory demands and rebuild trust. Remediation efforts typically involve comprehensive reviews of internal processes, significant investments in technology and personnel for compliance functions, enhanced training programs, and regular reporting to regulatory bodies. Such efforts are resource-intensive and can extend over several quarters, potentially impacting operational expenses and diverting management focus from other strategic initiatives. The history of large financial institutions facing similar compliance challenges suggests that the path to full resolution is often long and complex.
The repeated emphasis on remediation also brings into focus the broader issue of corporate governance and the "tone at the top." Regulatory bodies increasingly expect senior leadership to foster a culture of compliance that permeates all levels of the organization. The fact that a bank of Bank of America’s stature, with a CEO known for his focus on operational clean-up, is facing such a substantial fine for fundamental reporting failures, highlights the perpetual challenge of maintaining robust compliance frameworks within vast, complex global financial institutions.
Broader Industry Context and Implications
Bank of America’s challenging quarter unfolded within a broader backdrop of mixed results for the U.S. banking sector. The earnings season saw varied performances from other financial giants. JPMorgan Chase, for instance, reported missing both EPS and revenue estimates for the first time in years, indicating that even industry leaders faced unexpected headwinds. Goldman Sachs, Citigroup, and Wells Fargo also posted mixed results, suggesting a quarter marked by economic uncertainties, volatile market conditions, and evolving client demands.
The macroeconomic environment continued to play a significant role in shaping bank performance. While rising interest rates generally boosted net interest income across the sector, they also created volatility in fixed income markets, impacting trading revenues. Geopolitical tensions, persistent inflation, and the looming threat of a recession further contributed to an environment of caution among corporations and individual investors, which in turn affected investment banking activity and trading volumes.
For Bank of America specifically, the dual blow of a substantial regulatory fine and underperforming core businesses carries several long-term implications. Beyond the immediate financial cost, the reputational damage could affect client relationships, potentially making it harder to attract new business in competitive segments like investment banking and wealth management. Furthermore, sustained regulatory pressure and the need for extensive remediation could necessitate increased compliance spending, impacting the bank’s efficiency ratios and overall profitability in future quarters. The capital allocation strategy, including the pace of share repurchases, might also come under greater scrutiny as the bank navigates these challenges.
Ultimately, Bank of America’s third-quarter results serve as a stark reminder of the multifaceted challenges confronting large financial institutions. Balancing growth ambitions with rigorous risk management and unwavering regulatory compliance remains a complex endeavor, where lapses can lead to significant financial penalties and a dent in market confidence. The path forward for Bank of America will involve not only rectifying the identified compliance failures but also demonstrating to investors and regulators that its internal controls are truly robust and fit for purpose in an ever-evolving regulatory landscape.
