

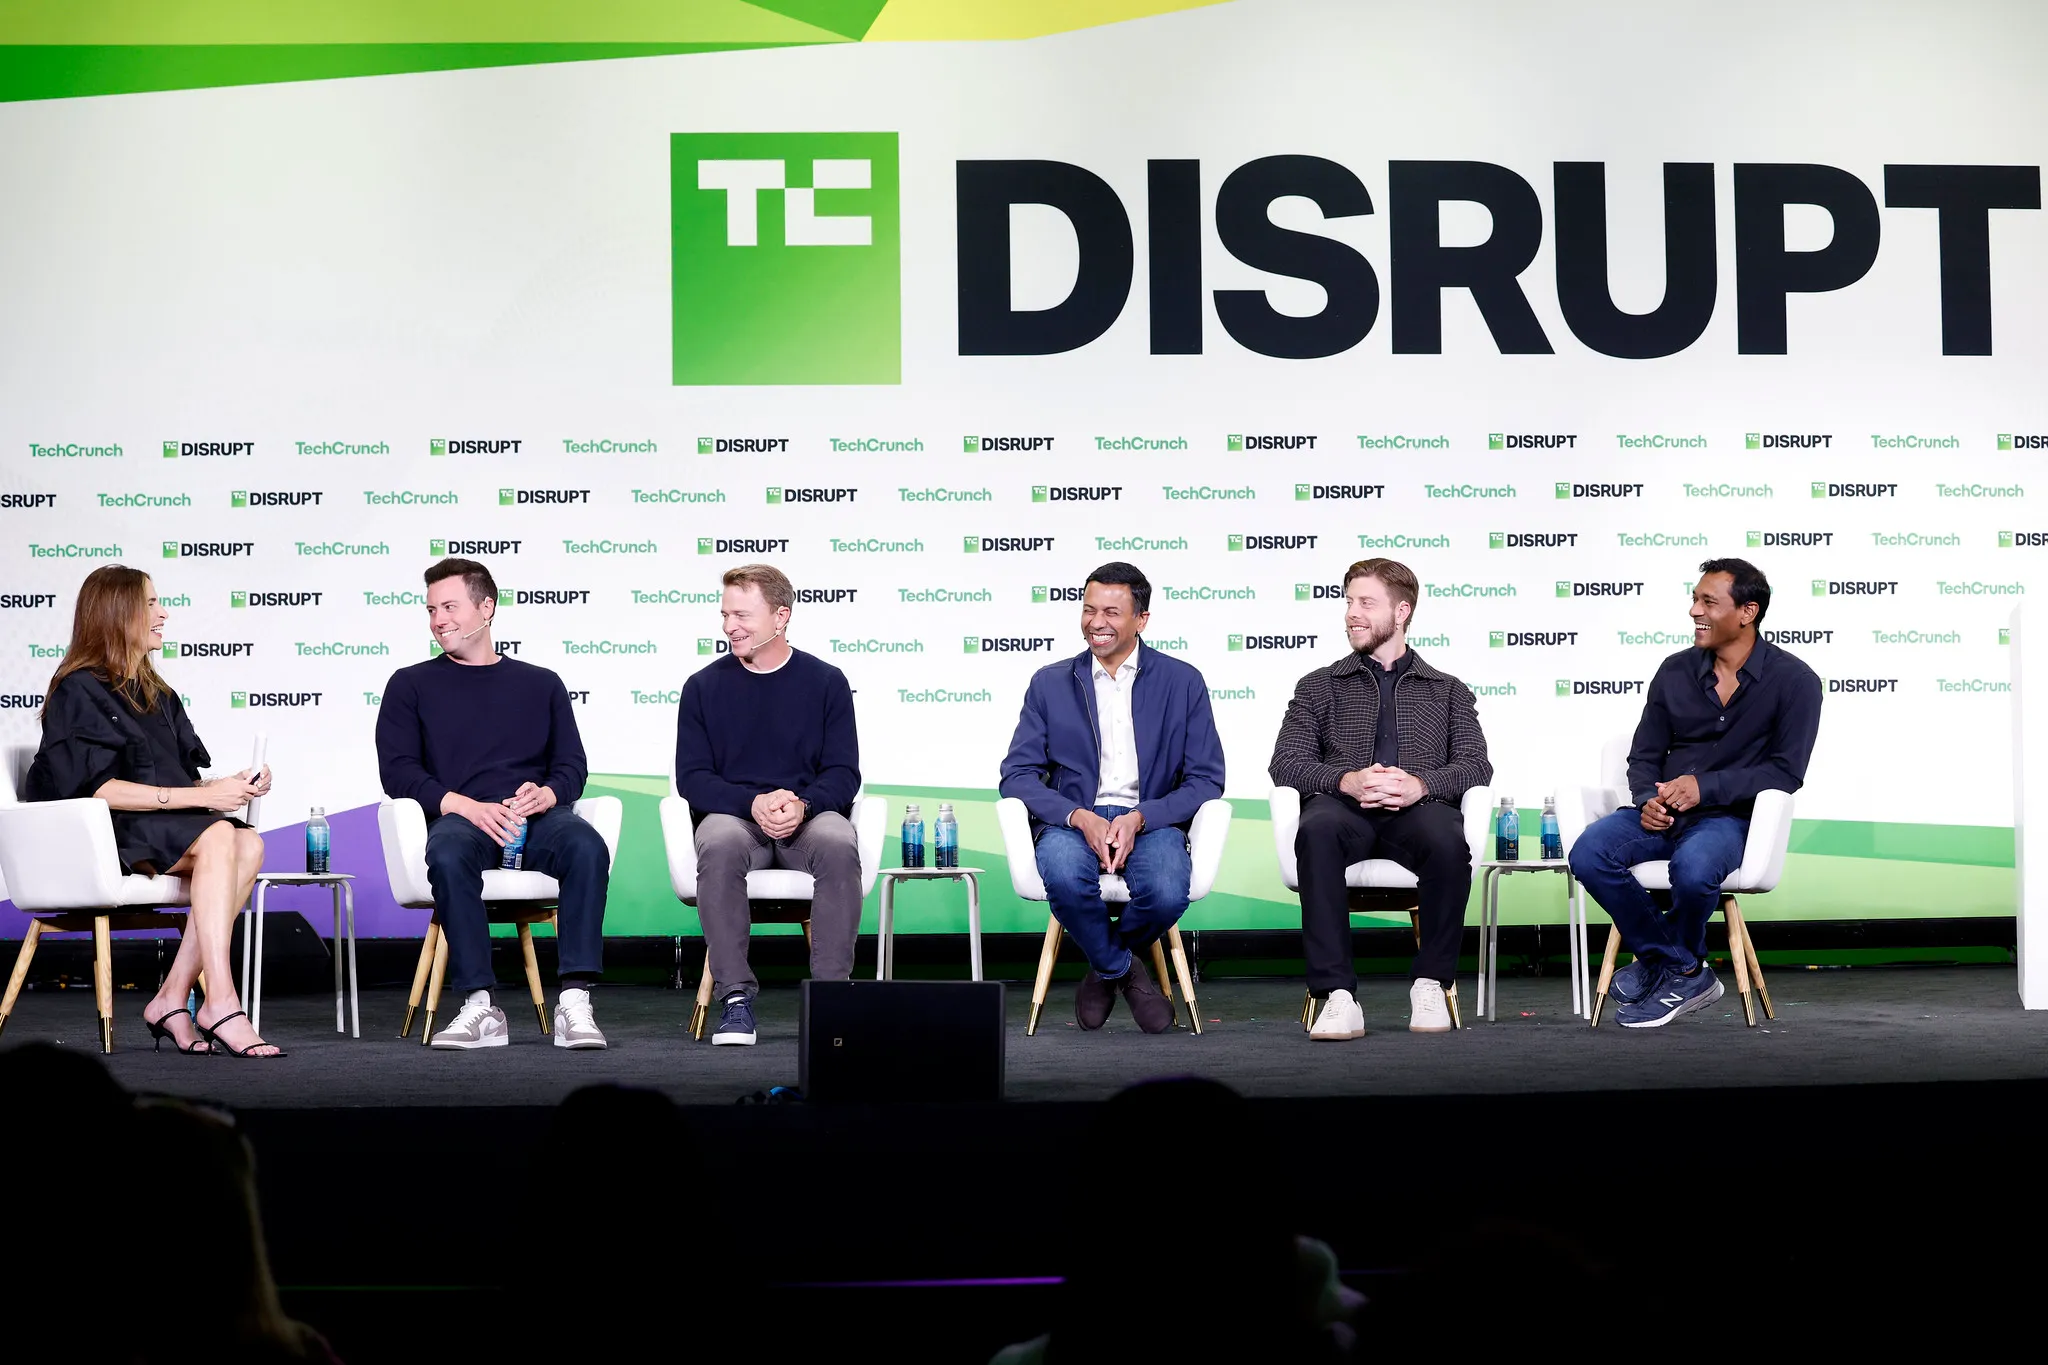
For decades, an unwritten but sacrosanct rule governed the venture capital ecosystem: a firm would not back two companies directly competing head-on. This principle, foundational to fostering trust and preventing conflicts of interest, has long been a cornerstone of investor-founder relationships. However, in the burgeoning era of artificial intelligence, this steadfast convention is not merely bending; it is rapidly approaching its breaking point. This profound shift was openly acknowledged earlier this week by partners at Benchmark, a firm renowned for its long-term, high-integrity partnerships, speaking candidly at TechCrunch Disrupt. Their admission signals a new, more complex reality for venture capitalists and the startups they fund, particularly within the hyper-competitive and rapidly evolving AI sector.
Historical Bedrock: The Genesis of VC’s "No-Compete" Covenant
The traditional "no-compete" rule in venture capital emerged from a practical necessity to maintain the delicate balance of trust inherent in early-stage investing. When a VC firm invests in a startup, it gains access to highly sensitive information: strategic plans, proprietary technology, financial forecasts, and intellectual property. The assurance that this information would not be shared with a direct rival, nor used to benefit a competing portfolio company, was paramount. This covenant allowed founders to open their books and minds to investors without fear of compromise, fostering deep, often decade-long partnerships that are critical for navigating the volatile journey from nascent idea to market leader. Historically, breaching this trust could lead to severe reputational damage, deter future founders, and even invite legal challenges, making adherence a matter of both ethical conduct and sound business practice. The rule was not merely about avoiding direct financial conflict but about preserving the integrity of the advisory relationship, ensuring VCs could genuinely advocate for and guide each company without inherent bias.
The AI Tsunami: Reshaping the Investment Playbook
The current AI boom, characterized by unprecedented innovation, staggering capital requirements, and rapidly blurring technological boundaries, has become the primary catalyst straining this long-held convention. Unlike previous technological cycles, the foundational nature of AI models means that many emerging applications share underlying technologies or target overlapping market segments. The cost of building software, as Benchmark partner Chetan Puttagunta observed, "effectively goes to zero" with advanced AI tools, empowering founders to be "incredibly ambitious." This ambition translates into a desire to claim vast "surface areas" of the market, inevitably leading companies to expand into each other’s territories over time.
Furthermore, the sheer scale of investment required for leading AI ventures has attracted an unusually high number of co-investors. Major AI labs like OpenAI and Anthropic, for instance, already share dozens of investors, a clear departure from past norms where such direct rivalry would have prompted VCs to choose sides. The allure of investing in potential industry titans, coupled with the rapid pace at which AI applications evolve and converge, makes it increasingly challenging for VCs to avoid what might, at inception, appear to be distinct ventures but quickly become competitors. The global AI market, projected to exceed $1.8 trillion by 2030, according to some analyses, is driving an investment frenzy, with venture funding in AI reaching record highs, compelling VCs to secure stakes in any company perceived to have significant potential, even if that means navigating complex competitive overlaps. This dynamic prioritizes securing a foothold in a transformative technology over strict adherence to traditional conflict avoidance.
A Flashpoint in the AI Wars: The Factory-Cognition Imbroglio
The theoretical strain on the "no-compete" rule manifested in a very public and acrimonious dispute at the end of September, highlighting the perilous ethical tightrope VCs now walk. Factory, a startup developing an AI agent for software creation, publicly accused Chris Degnan, a board observer and adviser, of "unethical conduct involving Cognition," its direct rival and the creator of the Devin coding agent. Factory’s CEO alleged that Degnan had discussed a potential job at Cognition while simultaneously being privy to Factory’s sensitive, board-level discussions.
Degnan swiftly countered, asserting he had already resigned from his advisory role at Factory before engaging in any discussions with Cognition, and vehemently denied sharing any confidential information. His subsequent announcement that he was joining Cognition as Chief Revenue Officer only intensified the controversy. The incident drew immediate attention from the wider VC community, notably from powerhouse investor Vinod Khosla. Khosla, whose firm Khosla Ventures notably backs both Factory and Cognition, publicly sided with Degnan on X (formerly Twitter), blasting Factory’s CEO and dismissing the company as "a struggling second-tier competitor."
This public spat exposed several layers of complexity. It underscored the lack of clear boundaries for board observers and advisers, whose roles can sometimes blur with those of full board members, especially regarding access to sensitive information. It also highlighted the inherent challenges for multi-stage VC firms like Khosla Ventures, which aim to invest broadly across a sector, inevitably leading to portfolio overlaps. The firm’s public stance, seemingly favoring one portfolio company over another in a direct conflict, raised significant questions about impartiality and the duty of care owed to all invested entities. The Factory-Cognition episode served as a stark, real-world example of the ethical dilemmas now facing investors navigating the AI gold rush.
Benchmark’s Candid Reckoning: A Bellwether for the Industry
Benchmark, a firm whose reputation is meticulously built on deep, loyal, 10-to-15-year partnerships with founders at the earliest stages, delivered a particularly telling assessment of the evolving landscape. When pressed at Disrupt on whether the pact against backing rivals still holds as portfolio companies inevitably expand into each other’s territory, its partners described the emerging conflicts as a matter of "necessity, not preference." This frankness from a firm synonymous with founder loyalty sent a clear signal across the industry: the rules are changing.
-
The Evolving Nature of Conflict: Eric Vishria, a Benchmark general partner, articulated the core challenge. "The harsh reality of this world is every company is evolving very quickly," he stated. Companies pivot, iterate, and expand at an unprecedented pace, driven by technological advancements and market opportunities. Vishria admitted that "you are going to get conflicts, and that’s just the reality of the current dynamic." While reassuring that Benchmark remains committed to each founder and maintains strict confidentiality regarding what it learns, he downplayed the practical impact of a VC sharing information, noting, "We are not product or technology experts." Vishria stressed that Benchmark has been "fortunate" to avoid "that type of insane direct conflict" seen in the Factory-Cognition case, suggesting an awareness of the severe repercussions of such public disputes. He emphasized that exclusivity remains "really important" at the very early stage Benchmark favors, but conceded, "But things are evolving. There’s no doubt about that." This statement encapsulates the firm’s attempt to reconcile its foundational principles with the undeniable pressures of the modern tech landscape.
-
AI’s Accelerating Effect: Chetan Puttagunta reinforced Vishria’s points, specifically attributing the acceleration of these conflicts to AI. The plummeting cost of software development empowers founders with "incredibly ambitious" visions. They envision and pursue broad "surface areas" for their products, inevitably leading to overlap. Puttagunta drew a crucial distinction between investing in a direct competitor "at the outset," which he termed "an easy answer" (implying a firm ‘no’), and a portfolio company expanding into another’s turf over time. "That happens," he noted, acknowledging the organic nature of competitive convergence in rapidly innovating fields.
-
Transparency as "Kryptonite": Peter Fenton, another Benchmark partner, perhaps offered the most poignant insight, labeling the issue "kryptonite" and the firm’s toughest problem. He articulated a spectrum of investor relationships. At one end, he placed the co-founder, who would never work on a competing company, embodying complete dedication. At the other, the public-market stock picker, who can own several rivals because their role is merely capital allocation, not shaping company strategy. Fenton positioned Benchmark closer to the co-founder end, emphasizing that transparency remains their "golden rule." He stressed that "There shouldn’t be the surprise after the fact." If a conflict does emerge, a founder should never feel shortchanged, he added. This underscores Benchmark’s attempt to manage conflicts through open communication and proactive disclosure, even as the landscape forces them into more complex situations.
Broader Implications: Trust, Ethics, and the Future of Venture Capital
Benchmark’s candid admission signals a paradigm shift that carries profound implications for the entire venture capital ecosystem, extending beyond individual firms to impact founders, ethical standards, and market dynamics.
-
Erosion of Founder Trust: The most immediate and critical consequence is the potential erosion of trust between founders and their investors. If founders can no longer be confident that their sensitive information is absolutely insulated from rivals sharing the same investment firm, they may become more guarded. This could lead to less transparent board meetings, reluctance to share strategic insights, and ultimately, a less effective advisory relationship, which is detrimental to startup growth. Founders might seek more explicit contractual agreements around data confidentiality and exclusivity, or even favor smaller, boutique firms perceived as less conflicted.
-
The Ethical Tightrope for VCs: Venture capital firms now face an increasingly intricate ethical tightrope. While they strive to maximize returns for their limited partners, this mandate must be balanced with their fiduciary duties and ethical obligations to portfolio companies. The Factory-Cognition dispute demonstrated the potential for reputational damage and legal challenges when these lines are crossed or perceived to be crossed. Firms will need to implement more robust internal protocols for managing conflicts, including information firewalls, designated lead investors for competing companies, and transparent disclosure policies. The industry may also see an increased demand for independent board members or advisers to mediate potential conflicts.
-
Market Concentration and Innovation: The trend of VCs backing multiple players in a nascent but high-growth sector like AI could lead to increased market concentration. If a few dominant VC firms hold significant stakes in all leading competitors, it could inadvertently dampen true competition or influence strategic decisions across the sector. While theoretically fostering innovation by ensuring capital flows to promising ventures, it also risks creating an oligopoly of investor influence, potentially limiting the entry and growth of truly disruptive, independent outsiders. This raises questions about antitrust implications in the long term, particularly if such investor overlaps become pervasive.
-
The Call for New Industry Norms: The current situation underscores the urgent need for the venture capital industry to collectively re-evaluate and redefine its ethical frameworks. The "unwritten rule" is no longer sufficient. New, more explicit guidelines may be required to address the complexities of a rapidly converging technological landscape. This could involve industry-wide best practices for managing competitive investments, clearer definitions of "direct competition" in the age of AI, and standardized protocols for handling conflicts of interest. Without such proactive measures, the industry risks an increase in public disputes, legal battles, and a fundamental breakdown of the trust that has historically fueled its success.
Conclusion
Benchmark isn’t declaring the traditional "no-compete" pact dead, but its partners’ collective sentiment is clear: the rule is evolving, and conflicts are an increasingly unavoidable reality in the AI era. When a firm that has built its formidable reputation on unwavering loyalty and founder-first principles candidly states that such conflicts are "kryptonite" and a matter of "necessity," it marks a significant moment. This shift challenges founders to scrutinize their investors more closely and forces venture capitalists to navigate an ever-more complex ethical and strategic landscape. The future of venture capital in the age of AI will depend on how effectively the industry can adapt its foundational principles to this new reality, balancing the pursuit of groundbreaking innovation with the enduring need for trust and ethical conduct.
