

The Mexican Peso (MXN) has demonstrated a notable rally against the US Dollar (USD), with the USD/MXN pair trading at 18.59, marking a decline of over 1.29% following the Democratic Party’s comprehensive victory in the US midterm elections. This "blue sweep," which sees Democrats poised to command both the US Senate and the House of Representatives starting in January 2027, has injected a sense of political stability into the world’s largest economy, a factor often favorable to emerging market currencies. However, this newfound optimism for the Peso is tempered by persistent geopolitical tensions, particularly the lack of a definitive agreement between the US and Iran, which could potentially destabilize global markets, boost safe-haven demand for the Greenback, and derail the MXN’s upward trajectory. Furthermore, the upcoming monetary policy decision by the Bank of Mexico (Banxico) later this week adds another layer of uncertainty to the currency pair’s immediate outlook.
The US Election Aftermath: A Tailwind for Emerging Markets
The perceived fading of US election-related risks has shifted market focus, with the outcome of the midterm elections providing a clearer political landscape for the next two years. A unified government, even if one party controls both legislative branches and the presidency, often implies greater legislative efficiency and predictability in policy-making, reducing domestic political gridlock. For emerging markets like Mexico, this stability is typically a positive signal, encouraging cross-border investment and trade. Analysts suggest that a Democrat-controlled Congress could potentially lead to more predictable trade policies, including those related to the United States-Mexico-Canada Agreement (USMCA), which underpins a significant portion of Mexico’s economy. This predictability, coupled with the ongoing trend of nearshoring – the relocation of manufacturing and supply chains closer to North American consumer markets – strengthens Mexico’s position as a key beneficiary of stable US economic and political conditions. The Peso, often seen as a proxy for broader emerging market sentiment and US-Mexico economic relations, tends to appreciate during periods of reduced political uncertainty in its northern neighbor. Historical data indicates that periods of perceived US political stability often correlate with increased foreign direct investment into Mexico and a stronger Peso, reflecting investor confidence in continued economic integration and trade.
Geopolitical Storm Clouds: US-Iran Tensions Resurface
While the domestic US political landscape appears to have cleared, the international arena presents significant headwinds. The spotlight has rapidly shifted to the Middle East, specifically the fraught relationship between Washington and Tehran. Recent reports, citing Arab diplomatic sources via Al Jadeed, indicate that the path of negotiations between the US and Iran might become clearer on Friday, suggesting an ongoing, albeit delicate, diplomatic process. However, simultaneously, the US Treasury has issued fresh Iran-related sanctions, signaling a continued hardline stance. US sources, also speaking with Al Jadeed, have warned that the conflict is entering a "delicate phase" before the new US Congress convenes. This period could see the White House potentially considering a resumption of attacks on Iran, escalating tensions dramatically.
The implications of such an escalation for global financial markets, and by extension the Mexican Peso, are profound. Heightened geopolitical instability typically triggers a flight to safety, with investors divesting from higher-risk emerging market assets and seeking refuge in traditional safe havens like the US Dollar, Japanese Yen, or Swiss Franc. Moreover, any significant escalation in the Middle East often leads to a spike in crude oil prices. While Mexico is a key oil exporter, the overall negative impact of global risk aversion and a stronger US Dollar could outweigh the benefits of higher oil revenues for the Peso. The specter of renewed conflict also introduces uncertainty into global supply chains and energy markets, dampening overall economic sentiment, which is detrimental to risk-sensitive currencies like the MXN. The historical context of US-Iran relations, marked by periods of intense sanctions and military posturing, underscores the volatility these tensions can inject into global financial systems.
Dissecting US Economic Data: A Mixed Picture for the Dollar
The recent raft of US economic data has painted a somewhat mixed picture, offering both reasons for caution and optimism regarding the strength of the US economy and, consequently, the US Dollar. The Institute for Supply Management (ISM) Services PMI, a closely watched indicator of business activity in the dominant services sector, registered 54.5. This figure, while still indicating expansion, was below both the previous month’s reading of 54.9 and analysts’ forecasts of 54.8. A deeper dive into the sub-components revealed a decline in "prices paid," which could be interpreted as a positive sign for inflation moderation. Conversely, the employment index within the PMI showed a modest recovery, suggesting resilience in the labor market despite broader economic cooling.

Complementing the ISM data, the ADP Employment Change report indicated that private companies hired more people than anticipated, reinforcing the notion of a robust, albeit perhaps decelerating, labor market. Furthermore, the US trade deficit narrowed in September, primarily driven by a rise in goods exports to a four-month high. A narrowing trade deficit is generally considered favorable for a nation’s currency, as it implies stronger demand for its goods and services internationally. Looking ahead, the US economic docket remains packed with crucial data releases. Investors will keenly await jobless claims figures on Thursday, followed by the highly anticipated Nonfarm Payrolls report on Friday. These labor market indicators are pivotal for the Federal Reserve’s assessment of economic health and its future monetary policy trajectory, directly influencing the US Dollar’s strength against its counterparts, including the Mexican Peso. Stronger-than-expected labor market data could strengthen the case for a hawkish Fed, potentially bolstering the USD.
Banxico’s Pivotal Monetary Policy Decision
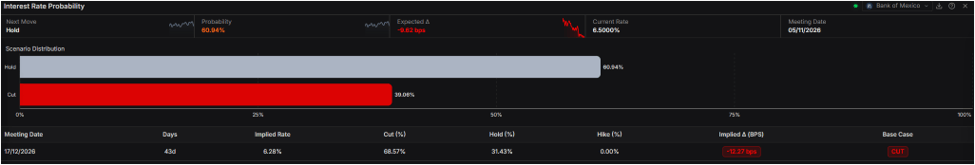
In Mexico, attention is squarely focused on the Bank of Mexico’s (Banxico) upcoming monetary policy decision scheduled for Thursday. While the domestic data docket has been relatively quiet, the central bank’s stance on interest rates is a critical determinant for the Peso’s value. According to the latest surveys of economists and the futures market, the overwhelming expectation is that Banxico will hold its benchmark interest rate unchanged at 6.50%. Prime Terminal data reveals that the odds for a hold stand at 60%, reflecting a consensus view that the central bank will prioritize stability amidst global uncertainties and its ongoing battle against inflation.
However, a significant minority, representing a 39% chance, suggests that Banxico could opt for a rate cut. This divergence in expectations highlights the complex balancing act faced by the central bank. A decision to hold rates would likely be predicated on maintaining a restrictive monetary policy stance to anchor inflation expectations and ensure that inflation converges towards its target range of 2-4%, with a midpoint of 3%. Such a move would generally be supportive of the Mexican Peso, as higher real interest rates make the currency more attractive to foreign investors seeking yield. Conversely, a surprise rate cut, while potentially aimed at stimulating economic growth, could exert downward pressure on the Peso by reducing its yield advantage and signaling concerns about Mexico’s economic trajectory.
Banxico’s primary objective is to maintain inflation at low and stable levels. When inflation is elevated, as it has been globally, the central bank typically raises interest rates to cool demand. Higher rates increase borrowing costs, thereby slowing economic activity and curbing price pressures. The decision on Thursday will therefore reflect Banxico’s assessment of the current inflationary environment, domestic economic growth prospects, and the potential impact of global financial conditions. Any deviation from the widely anticipated hold could trigger significant volatility in the USD/MXN pair.
Technical Outlook: Navigating the USD/MXN Landscape
From a technical perspective, the USD/MXN pair, currently trading around 18.6012, exhibits a clear bullish bias on the daily chart. This bias is underscored by the spot price consolidating well above a triple simple moving average (SMA) cluster, whose latest reading is approximately 17.8508. The pair has also decisively held above its former downward resistance trend line, which now acts as a distant reference point around 14.7081. This sustained positioning above key moving averages indicates underlying buying interest and a robust upward momentum.
The Relative Strength Index (RSI 14-day), a momentum oscillator, stands at 56.53. This reading suggests that while the buying momentum remains positive, it has cooled from prior overbought extremes. This implies a steady, albeit less aggressive, upside potential rather than an immediate exhaustion of the bullish trend.
Looking at potential price movements, immediate technical support for the USD/MXN pair is hinted by the aforementioned triple simple moving average area at 17.85. This zone is expected to act as the initial cushion against any potential pullback. Should this level be breached, stronger horizontal demand is anticipated around 16.89, where previous price action suggests a confluence of buying interest. Deeper retracements, though requiring a significant reversal from the current bullish configuration, would likely find additional structural backing around the old trend-line break region near 14.71. For the bullish trend to be fundamentally challenged, the pair would need to breach these key support levels with conviction, signaling a shift in market sentiment.
Broader Context: Understanding the Mexican Peso’s Resilience and Vulnerabilities
The Mexican Peso stands as the most traded currency among its Latin American counterparts, making its valuation a critical indicator of regional economic health and global risk appetite. Its value is broadly influenced by a confluence of factors: the performance of the Mexican economy, Banxico’s monetary policy, the volume of foreign direct investment, and even the substantial remittances sent by Mexicans living abroad, particularly in the United States.
Geopolitical and economic trends also play a significant role. The "nearshoring" phenomenon, driven by firms seeking to shorten supply chains and reduce geopolitical risks, has positioned Mexico as a key manufacturing hub in the American continent, attracting investment and bolstering the Peso. Furthermore, as a key oil exporter, Mexico’s currency can be influenced by fluctuations in global crude oil prices, though this correlation can be complex given broader risk sentiment.
Banxico’s commitment to maintaining inflation within its target band of 2% to 4% (with a 3% midpoint) through appropriate interest rate settings is paramount. Higher interest rates, generally, make the MXN more attractive to carry-trade investors, strengthening the currency. Conversely, lower rates tend to weaken it. Macroeconomic data releases, including GDP growth, unemployment rates, and consumer confidence, are crucial for assessing the economy’s health. A strong economy typically attracts foreign investment and may prompt Banxico to maintain higher rates, supporting the MXN.
As an emerging-market currency, the Mexican Peso thrives during "risk-on" periods, when investors are confident and willing to engage with higher-risk, higher-yield assets. Conversely, during periods of market turbulence or economic uncertainty (often termed "risk-off"), investors tend to liquidate riskier assets and flock to safe havens, leading to MXN depreciation. The current environment, characterized by US political stability alongside significant geopolitical risks, presents a complex backdrop where these competing forces will likely dictate the Peso’s near-term trajectory.
Conclusion: A Tense Balance of Forces
The Mexican Peso’s recent rally, ignited by the clarity of the US midterm election results, underscores the profound interconnectedness of US domestic politics and emerging market performance. The Democratic "blue sweep" has offered a dose of predictability that is inherently supportive of cross-border investment and trade, benefiting the MXN. However, this positive momentum is precariously balanced against potent external threats and domestic monetary policy considerations. The escalating US-Iran tensions represent a significant wildcard, capable of triggering a swift reversal in risk sentiment and a flight to the US Dollar. Simultaneously, Banxico’s impending rate decision will either reinforce the Peso’s yield appeal or introduce uncertainty, depending on whether it opts for a hold or a surprise cut. As such, while the immediate aftermath of the US elections has been favorable for the Peso, the coming days are set to test its resilience against a backdrop of complex geopolitical dynamics and critical central bank pronouncements, ensuring continued volatility for the USD/MXN pair.
