

MANABU MORIMOTO, SHUNSUKE USHIGOME and JADA NAGUMO
October 2, 2026 17:11 JST
Updated on October 2, 2026 20:13 JST
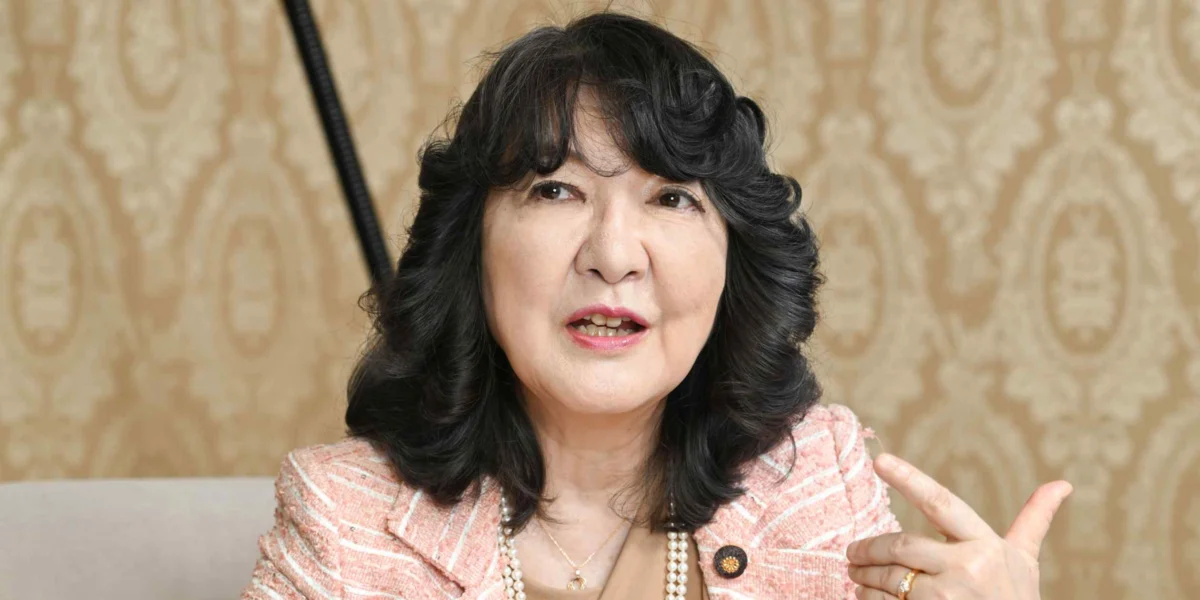
TOKYO — In a clear assertion of governmental resolve, Japanese Finance Minister Satsuki Katayama declared that Prime Minister Sanae Takaichi’s administration is unequivocally united in its assessment that the era of reflationary policies has concluded. Speaking in an exclusive interview with Nikkei in Tokyo on October 1st, Katayama affirmed the government’s steadfast support for the Bank of Japan’s ongoing endeavors to combat escalating inflation, a critical undertaking as Tokyo grapples with a persistently weakening yen.
The Finance Minister’s remarks come at a pivotal moment, following the release of a summary of opinions from the Bank of Japan’s recent monetary policy meeting. This summary, intended to offer transparency into the central bank’s deliberations, has inadvertently sparked debate and raised questions among market participants and economic observers regarding the precise trajectory and nuances of the BOJ’s policy stance. Katayama’s emphatic statement seeks to quell any emergent anxieties and reinforce a singular, cohesive message from the highest echelons of Japanese economic policymaking.
Navigating Inflationary Headwinds and Yen Volatility
The global economic landscape in late 2026 continues to be defined by persistent inflationary pressures, a phenomenon that has challenged central banks worldwide. Japan, while perhaps initially appearing more insulated, has not been immune. Rising energy costs, supply chain disruptions exacerbated by geopolitical tensions, and an increase in domestic demand have collectively contributed to an uptick in the consumer price index (CPI).
According to the latest available data from the Statistics Bureau of Japan, the core CPI, which excludes volatile fresh food prices, registered a year-on-year increase of 3.2% in August 2026. This figure marks a significant acceleration from the 2.5% recorded in the same period of the previous year and has pushed inflation above the Bank of Japan’s long-standing 2% target. While a moderate level of inflation is often seen as a sign of a healthy, growing economy, the current pace and underlying drivers have prompted increased scrutiny from policymakers.
Simultaneously, the Japanese yen has experienced considerable depreciation against major global currencies. As of early October 2026, the USD/JPY exchange rate hovers around 148 yen, a level not seen in several years. This weakening yen, while potentially beneficial for Japanese exporters by making their goods cheaper abroad, poses significant challenges for an import-reliant nation like Japan. It drives up the cost of imported goods, including essential commodities like oil and raw materials, thereby feeding directly into domestic inflation and eroding the purchasing power of consumers.
It is against this backdrop of dual challenges – managing inflation and stemming yen depreciation – that the government’s unified stance on policy direction becomes particularly significant. The Takaichi administration, since taking office, has signaled a shift in economic strategy, moving away from the ultra-accommodative monetary policies that characterized much of the preceding decade. The emphasis is now on fostering sustainable growth driven by structural reforms and responsible fiscal management, rather than relying solely on monetary stimulus.
The Bank of Japan’s Evolving Mandate
The Bank of Japan, under Governor Haruhiko Kuroda’s successor, has been meticulously recalibrating its approach. While maintaining a commitment to price stability, the central bank has begun to signal a gradual normalization of its monetary policy. This has included subtle adjustments to its yield curve control (YCC) framework and, more recently, discussions about the potential unwinding of its massive balance sheet accumulated through years of quantitative easing.
The summary of opinions from the latest Monetary Policy Meeting, released on September 28, 2026, provided insights into the diverse perspectives within the BOJ’s Policy Board. While a majority acknowledged the need to address inflationary pressures and the yen’s weakness, some members expressed caution about the pace of policy tightening, citing concerns about the potential impact on economic growth and financial market stability. This divergence of views, though normal in any central bank, has been interpreted by some as a sign of internal debate and potential uncertainty about the optimal path forward.
One particular point of discussion in the summary revolved around the timing and magnitude of any future interest rate hikes. While the prevailing sentiment leaned towards a gradual increase, the absence of a clear, immediate consensus on the precise trigger or timeline has fueled speculation. Some analysts interpreted this as a signal that the BOJ might be more inclined to allow inflation to moderate naturally before taking decisive action, while others saw it as a preparatory step towards a more aggressive stance if inflation proves more persistent.
Finance Minister Katayama’s Call for Unity
Finance Minister Katayama’s intervention is designed to provide a definitive counterpoint to such speculative interpretations. By explicitly stating that the government views "reflationary policy is over," she is signaling a clear departure from the past and a commitment to a new economic paradigm. This statement carries significant weight, as it aligns the fiscal authority with the monetary authority, presenting a united front to both domestic and international audiences.
"The Prime Minister and I, along with the entire cabinet, are in complete agreement," Katayama stated firmly during the interview. "We believe that the conditions that necessitated the extensive reflationary policies of the past are no longer present. Our focus now is on fostering sustainable, demand-driven growth and ensuring the stability of our currency. The Bank of Japan’s efforts to combat inflation are crucial in this regard, and we fully support their mandate."
Katayama’s emphasis on unity is particularly pertinent given the historical context of the Bank of Japan’s operational independence, a cornerstone of modern central banking. However, in practice, close coordination between the Ministry of Finance and the central bank is vital for effective macroeconomic management. Her statement suggests that this coordination is robust and that the government’s economic objectives are closely aligned with the BOJ’s evolving strategy.
Implications for Economic Policy and Market Reaction
The implications of this unified stance are multifaceted. Firstly, it signals to domestic businesses and households that the era of extraordinarily low interest rates may be drawing to a close, encouraging a more prudent approach to investment and consumption. Secondly, it sends a clear message to international investors and currency markets that Japan is committed to tackling inflation and supporting the yen. This could help to stabilize the currency and attract foreign investment.
The market reaction to Katayama’s comments is likely to be closely watched. While some investors may welcome the clarity and assurance of a unified government policy, others might remain cautious, awaiting further concrete actions from the Bank of Japan. The precise wording of the BOJ’s future communications and its actual policy adjustments will be critical in shaping market sentiment.
A Look at the Historical Context
Japan’s economic policy landscape has been shaped by decades of deflationary pressures and a prolonged period of low growth, often referred to as the "lost decades." In response, the Bank of Japan, under various governors, implemented aggressive monetary easing measures, including negative interest rates and large-scale asset purchases, to stimulate the economy and achieve its 2% inflation target. This period, often termed "Abenomics" under former Prime Minister Shinzo Abe, was largely characterized by a strong emphasis on monetary stimulus.
However, the global shift towards higher inflation in the early 2020s, coupled with Japan’s own inflationary pressures and the yen’s depreciation, has necessitated a reassessment of this strategy. Prime Minister Takaichi’s administration has been vocal about the need for a more balanced approach, incorporating structural reforms and fiscal prudence alongside monetary policy adjustments. Katayama’s statement on the end of reflationary policy is a significant public articulation of this strategic pivot.
Broader Economic Outlook and Future Challenges
The path forward for the Japanese economy will undoubtedly be complex. While the government expresses confidence in its unified approach, several challenges remain.
- Inflation Persistence: The sustainability of current inflation levels is a key concern. If inflationary pressures prove to be more entrenched than anticipated, the Bank of Japan may face difficult decisions regarding the pace and extent of monetary tightening, potentially risking economic growth.
- Yen Stability: While the government aims to counter yen weakness, global economic factors, such as interest rate differentials with other major economies and geopolitical risks, will continue to influence currency movements.
- Structural Reforms: The success of the Takaichi administration’s long-term economic strategy hinges on the effective implementation of structural reforms aimed at boosting productivity, encouraging innovation, and addressing demographic challenges, such as an aging population and a declining birthrate.
- Fiscal Sustainability: Balancing the need for economic stimulus with fiscal responsibility will be a delicate act. The government will need to manage public debt while investing in areas that promote long-term growth and social well-being.
In conclusion, Finance Minister Satsuki Katayama’s declaration of governmental unity in ending reflationary policy marks a significant moment in Japan’s economic narrative. It signals a clear intention to navigate the current challenges of inflation and yen depreciation with a more calibrated and sustainable approach. As the Bank of Japan continues its policy recalibration, the coordinated efforts of the government and the central bank will be paramount in shaping Japan’s economic future and restoring confidence in its long-term prosperity. The coming months will be critical in observing how this declared unity translates into concrete policy actions and market responses.
