

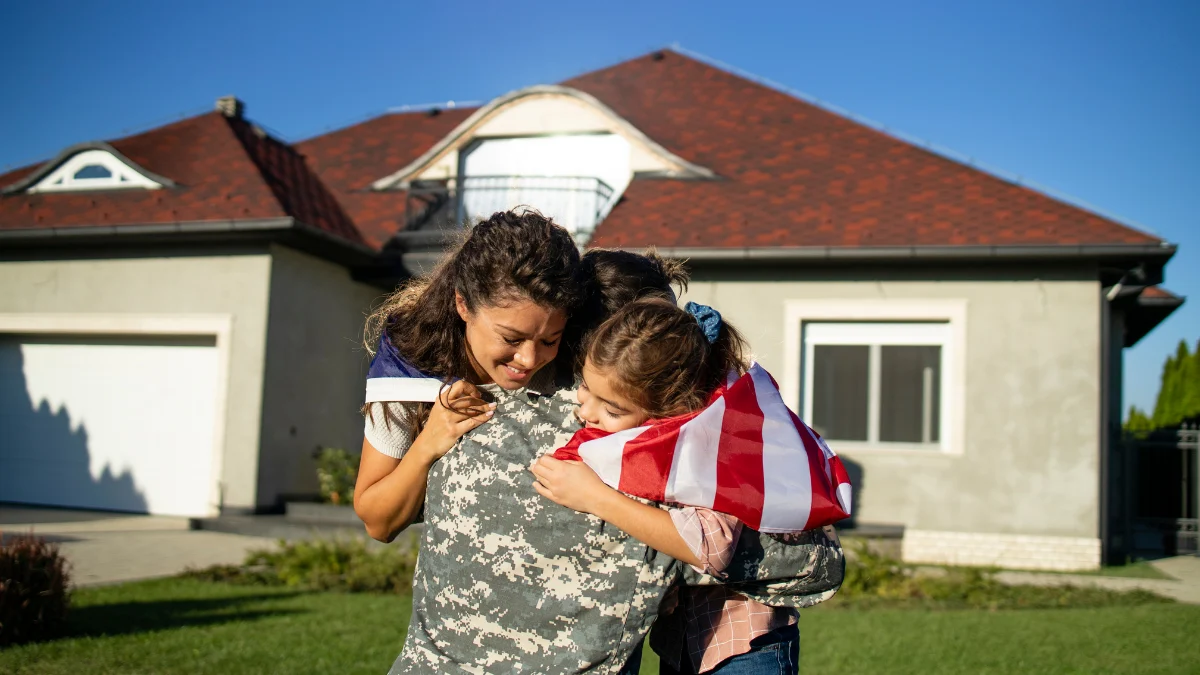
The transition from active-duty military service to civilian life represents one of the most significant shifts an individual and their family can undergo. For many of the approximately 200,000 service members who transition out of the United States Armed Forces annually, the search for a permanent residence is not merely a logistical hurdle but a foundational step toward establishing a new identity. After years of nomadic existence defined by Permanent Change of Station (PCS) orders, the ability to "put down roots" carries profound emotional and economic weight. However, as industry data and personal testimonies suggest, the path to stable homeownership is fraught with unique challenges that require specialized knowledge from mortgage professionals and robust support from the private sector.
The Cycle of Disruption: The Reality of Military Relocation
Military life is characterized by a state of perpetual motion. According to data from the Military Family Advisory Network (MFAN), military families move, on average, every 2.5 years. This frequency is roughly ten times more often than civilian families. These moves are rarely matters of choice; they are dictated by the needs of the Department of Defense, often requiring families to uproot their lives with only a few months of notice.
The impact of this constant relocation is cumulative. Beyond the physical exhaustion of packing and unpacking—which many families report doing upwards of ten times over a twenty-year career—there is a significant social and psychological cost. The "renter’s mindset" often takes hold, where families hesitate to decorate, renovate, or even fully unpack, knowing that another move is imminent. This creates a sense of detachment from local communities, making it difficult for service members and their spouses to build the long-term social capital that civilians often take for granted.
The Economic Hurdles of Reintegration
When the time finally comes to transition to civilian life, the hurdles shift from logistical to economic. The 2025 report from the Bureau of Labor Statistics (BLS) highlights a critical demographic reality: 5.8 million veterans, or approximately 34% of the total U.S. veteran population, possess a service-connected disability. These health challenges can complicate the search for civilian employment and dictate specific requirements for housing, such as accessibility features or proximity to Veterans Affairs (VA) medical facilities.
Simultaneously, military spouses often face a "career gap" or "underemployment trap." Repeated moves frequently force spouses to restart their careers from entry-level positions or abandon professional licenses that do not transfer across state lines. By the time a family settles into a "forever home," the spouse may be tasked with rebuilding a career from scratch, adding financial pressure to the household during the mortgage application process.
The VA Home Loan: A Cornerstone of Veteran Homeownership
The VA home loan benefit remains one of the most powerful tools available for veterans seeking to enter the housing market. Established as part of the 1944 GI Bill, the program was designed to level the playing field for returning service members who had not had the opportunity to build credit or accumulate savings for a traditional down payment.
In 2025, the National Association of REALTORS® (NAR) reported that 55% of veteran homebuyers utilized VA financing. The program offers several distinct advantages, including:
- Zero Down Payment: The ability to purchase a home without a traditional 20% or even 3.5% down payment.
- No Private Mortgage Insurance (PMI): Unlike conventional loans with low down payments, VA loans do not require monthly PMI, significantly reducing the monthly carrying cost.
- Competitive Interest Rates: VA loans typically offer lower interest rates than conventional or FHA loans.
- Limitation on Closing Costs: The VA limits the types of fees lenders can charge veteran borrowers.
Despite these benefits, the program is often misunderstood by both borrowers and real estate professionals. There is a persistent myth in the industry that VA loans are more difficult to close or that VA appraisals are overly stringent. This misinformation can lead to veteran offers being rejected in competitive "bidding war" environments, a phenomenon that housing advocates have worked tirelessly to combat through education.
The Role of Mortgage Professionals in the Transition Process
For mortgage originators and brokers, working with military families requires a level of expertise that goes beyond standard loan processing. Professional development in this sector must be ongoing, as VA guidelines evolve. For instance, many professionals remain unaware that the VA loan benefit is not a "one-time use" entitlement. Veterans can use the benefit multiple times throughout their lives, and in some cases, can even have two active VA loans simultaneously if they have sufficient remaining entitlement.
Expertise also involves empathy and comprehensive financial counseling. Mortgage professionals are often the first civilians to view a veteran’s full financial picture during the transition. They must be prepared to ask the right questions: What is the primary motivation for this move? How does the monthly payment fit into a budget that may now rely on disability income or a new civilian salary? By evaluating VA financing alongside other options, such as FHA or conventional loans, mortgage professionals ensure that the veteran is making a choice that supports long-term wealth building rather than just immediate acquisition.
Corporate Responsibility and the DoD SkillBridge Program
The responsibility for supporting military transitions extends into the corporate boardroom. Employers across all sectors, including the mortgage and financial services industries, have a vested interest in recruiting veterans, who often possess high levels of leadership, discipline, and technical proficiency.
One of the most effective conduits for this support is the Department of Defense (DoD) SkillBridge program. This initiative allows service members to spend their final 180 days of service in a civilian work environment through internships, apprenticeships, or job training, all while continuing to receive their military pay and benefits.
For employers, becoming a SkillBridge provider offers a "no-cost" opportunity to evaluate talent while providing the service member with invaluable civilian work experience. In the mortgage industry, this can be used to train veterans as loan officers, underwriters, or analysts, creating a pipeline of professionals who personally understand the needs of the clients they serve.
Community Support Beyond the Closing Table
A house becomes a home only when the family feels supported by the surrounding community. This is particularly true for veterans dealing with the invisible wounds of war. Organizations such as Camp Hope have become vital in this regard, providing residential programs for combat-related trauma and support for families at no cost.
Food insecurity is another localized challenge that often goes unseen. The Stronghold Food Pantry and similar organizations provide essential assistance to military families who may be struggling during the gap between their last military paycheck and their first civilian one. Furthermore, wellness-focused groups like InDependent Wellness offer programs specifically for military spouses, addressing the isolation and health challenges that come with years of frequent relocation.
For corporations looking to fulfill their social responsibility mandates, these organizations offer a roadmap. Financial contributions are essential, but "boots on the ground" volunteerism and mentorship programs can be equally impactful in helping a veteran family feel that they have truly arrived in a community that values their presence.
Analysis: The Broader Implications of Stable Housing
The implications of veteran homeownership extend far beyond the individual family. Economically, veteran homeowners contribute to the stability of local tax bases and the growth of the housing market. Socially, the transition from "active duty" to "active neighbor" fosters community cohesion.
When a veteran family is unable to find stable housing, the risk of homelessness, mental health crises, and financial instability increases exponentially. Therefore, the work of mortgage professionals and community advocates is a matter of national interest. By ensuring that the VA loan benefit is accessible and that the transition into civilian careers is seamless, the private sector plays a critical role in upholding the nation’s promise to those who served.
A Call to Action for Industry Stakeholders
As the nation reflects on the service of its veterans, the call to action for the housing and employment sectors is clear. It is not enough to offer a "thank you for your service" at a closing table or in a job interview. Support must be substantive, informed, and sustained.
Mortgage professionals should commit to a deeper study of VA guidelines, moving beyond the basics to understand the nuances of entitlement and restoration. Employers should look toward programs like SkillBridge to diversify their workforce with veteran talent. And perhaps most importantly, all stakeholders must recognize that for a military family, a home is more than an asset—it is the place where, after years of movement and uncertainty, they can finally breathe.
The transition from military to civilian life is a complex journey, but with the right support systems in place, it can also be a homecoming in the truest sense of the word. To honor their service, the industries that build and finance American communities must ensure they are equipped to serve those who have spent their lives serving the country.
