

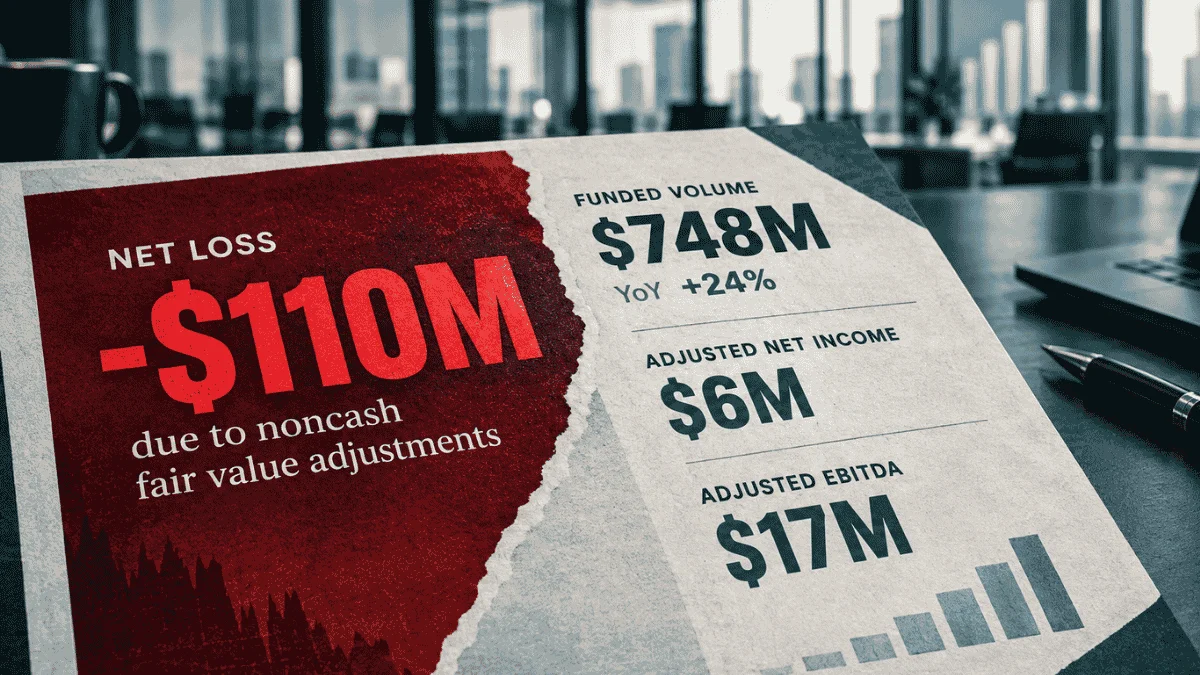
Finance of America (FOA), a leading provider of home equity-based retirement solutions, announced a net loss of $110 million for the third quarter of 2026, a result heavily influenced by significant noncash fair value adjustments. Despite the statutory loss, the Plano, Texas-based company reported robust operational growth, characterized by a 24% year-over-year increase in funded loan volumes. The divergence between the company’s bottom-line figures and its operational performance highlights the complexities of navigating a shifting interest rate environment, which saw the Federal Reserve pivot from a period of monetary easing to aggressive rate hikes during the quarter.
For the three-month period ending September 30, 2026, Finance of America recorded funded origination volumes of $748 million, up from $603 million in the third quarter of 2025. This momentum contributed to a year-to-date funded volume of $2.07 billion, representing a 17% increase over the first nine months of the previous year. However, the GAAP (Generally Accepted Accounting Principles) financial results were overshadowed by $125 million in noncash fair value adjustments related to the company’s retained interests in securitizations and other portfolio assets. These adjustments led to a basic loss of $5.24 per share, a sharp decline compared to the 98-cent loss per share reported in the same quarter of 2025.
The Macroeconomic Backdrop and the Federal Reserve Pivot
The third quarter of 2026 was marked by a significant shift in the U.S. economic landscape. After a series of interest rate cuts earlier in the decade designed to stimulate the housing market, the Federal Reserve reversed course in response to persistent inflationary pressures. This "pivot" caught many market participants off guard, leading to a surge in benchmark yields. Specifically, the 10-year Treasury yield—a critical benchmark for long-term mortgage pricing—climbed by more than 75 basis points during the quarter.
CEO Graham Fleming addressed these headwinds during the company’s quarterly earnings call, noting that while the interest rate environment created immediate pressure on earnings and margins, the company views the impact as a transitory phase. "The third quarter was a challenging rate environment," Fleming told investors. "The reaction to the Fed’s pivot to raising rates and elevated inflation drove near-term pressure on earnings, but we believe this impact is temporary. We have already taken steps to improve margins and have made the necessary changes to product pricing."
The rapid rise in rates typically compresses the "gain-on-sale" margins for mortgage originators, as the cost of funding increases faster than the rates that can be passed on to consumers in real-time. For FOA, this was reflected in the retirement solutions revenue margin, which dipped to 9% in Q3 2026, compared to 11.3% in the prior-year period and a historical average of 10.7% since the beginning of 2024.
Retirement Solutions: Growth Amidst Margin Compression
Finance of America’s Retirement Solutions segment remains the core engine of the company’s business model. This division specializes in Home Equity Conversion Mortgages (HECMs) and proprietary "HomeSafe" reverse mortgage products, which allow older homeowners to tap into their home equity to fund retirement.
Despite the margin pressure, the segment’s volume growth remained a bright spot. The $748 million in funded volume was driven by a diversified product suite. According to FOA President Kristen Sieffert, the company’s submission volumes have increased by an average of 21% annually since 2023. In Q3 2026 specifically, HECM volumes grew by 14% year over year, while the company’s proprietary HomeSafe first-lien products rose by 15%. Most notably, HomeSafe "seconds"—a product designed for homeowners who wish to access equity without refinancing their existing low-rate first mortgage—surged by 63%.
"Our platform continues to demonstrate strength," Sieffert said. "The growth in our HomeSafe second product is particularly encouraging, as it addresses a specific need for retirees who are reluctant to give up the favorable interest rates they secured on their primary mortgages in previous years."
However, the segment’s financial metrics reflected the broader market volatility. Revenue for the retirement solutions division totaled $67 million, a slight decrease from the $74 million reported in the second quarter of 2026 and a 1% decline from the third quarter of 2025. Pretax income for the segment fell to $3 million, down from $10 million a year earlier, while adjusted net income settled at $9 million, compared to $20 million in Q3 2025.
Portfolio Management and Asset Valuation
The Portfolio Management segment, which oversees the company’s vast array of mortgage-backed securities and servicing rights, faced the brunt of the noncash adjustments. The segment reported a pretax loss of $138 million for the quarter, a significant increase from the $11 million loss recorded in the third quarter of 2025.
The primary driver of this loss was the negative fair value adjustment on retained interests. In mortgage banking, companies must value their held assets based on current market conditions. When interest rates rise, the market value of existing fixed-rate assets typically falls, requiring a "write-down" on the balance sheet. Because these are noncash charges, they do not represent an actual outflow of capital, but they do impact the reported net income and book value.
On an adjusted basis, which strips out these noncash fluctuations, the portfolio management segment remained profitable, posting an adjusted net income of $11 million. Furthermore, the segment’s Assets Under Management (AUM) grew to $37.4 billion, a 23% increase year over year. This growth was bolstered by new originations and the strategic acquisition of Onity Mortgage Corp.’s HECM servicing portfolio, which was finalized on July 1, 2026. This acquisition has significantly expanded FOA’s footprint in the reverse mortgage servicing space, providing a steady stream of recurring revenue.
Liquidity, Debt Management, and Capital Position
Despite the quarterly net loss, Finance of America strengthened its liquidity position. The company ended the third quarter with $118 million in cash and cash equivalents, up from $85 million at the end of June 2026. This increase was attributed to efficient cash generation from its origination platform and successful capital markets activities, including the securitization of home equity loans.
The company also remained committed to deleveraging its balance sheet. Chief Financial Officer Matt Engel announced that FOA expects to complete a $60 million paydown of its senior secured notes in November 2026. This move is part of a broader strategy to reduce interest expenses and improve the company’s overall credit profile.
As of September 30, 2026, total equity stood at $307 million, with $259 million attributable to common stock. The company reported a book value of $28.08 per common share. Management emphasized that the underlying fundamentals of the business remain intact, with the book value providing a floor for the company’s intrinsic worth despite the volatility in the equity markets.
Chronology of Strategic Evolution (2023–2026)
To understand FOA’s current position, it is necessary to look at the strategic pivot the company began in 2023. Following a period of restructuring where the company exited its traditional forward mortgage business to focus exclusively on home equity and retirement solutions, FOA has maintained a consistent growth trajectory.
- 2023-2024: FOA consolidated its operations, focusing on the "Silver Tsunami"—the demographic shift as Baby Boomers entered retirement with record levels of home equity but insufficient cash savings.
- 2025: The company introduced expanded proprietary products, including the HomeSafe suite, to cater to high-value homes that exceeded FHA loan limits.
- Early 2026: FOA capitalized on a brief window of falling rates to boost submission volumes and streamline its digital application process.
- Q3 2026: The company navigated a "stress test" environment as the Federal Reserve unexpectedly raised rates to combat a mid-year inflation spike.
This timeline demonstrates a company that has traded volume stability for a specialized niche. While the niche is highly sensitive to interest rate valuations, it benefits from a lack of direct competition compared to the crowded traditional mortgage market.
Future Outlook and Industry Implications
Looking ahead to the fourth quarter of 2026, Finance of America’s management remains optimistic. CFO Matt Engel provided guidance for funded volumes in the range of $3.1 billion to $3.4 billion for the full year. This projection is supported by what the company describes as "ongoing conversion improvements" and favorable consumer demographics.
The broader implications for the housing and retirement industry are significant. As traditional pension plans disappear and Social Security faces long-term sustainability questions, the role of home equity in retirement planning has moved from a "last resort" to a strategic tool. FOA’s ability to grow its volume by 24% in a rising-rate environment suggests that consumer demand for liquidity is outweighing the increased cost of borrowing.
Industry analysts suggest that if Finance of America can successfully return its margins to historical levels by the first half of 2027, as CEO Graham Fleming predicted, the company will be well-positioned to capitalize on any future stabilization of the Treasury market. For now, the company remains a case study in the modern financial sector: a business seeing record operational demand while simultaneously wrestling with the accounting complexities of a volatile global economy.
As the company prepares for the final months of the year, the focus remains on operational efficiency and the conversion of its high submission volumes into funded loans. With a strengthened cash position and a clear path toward debt reduction, Finance of America is betting that its long-term demographic tailwinds will eventually outpace the short-term noise of fair value accounting and Federal Reserve policy shifts.
