

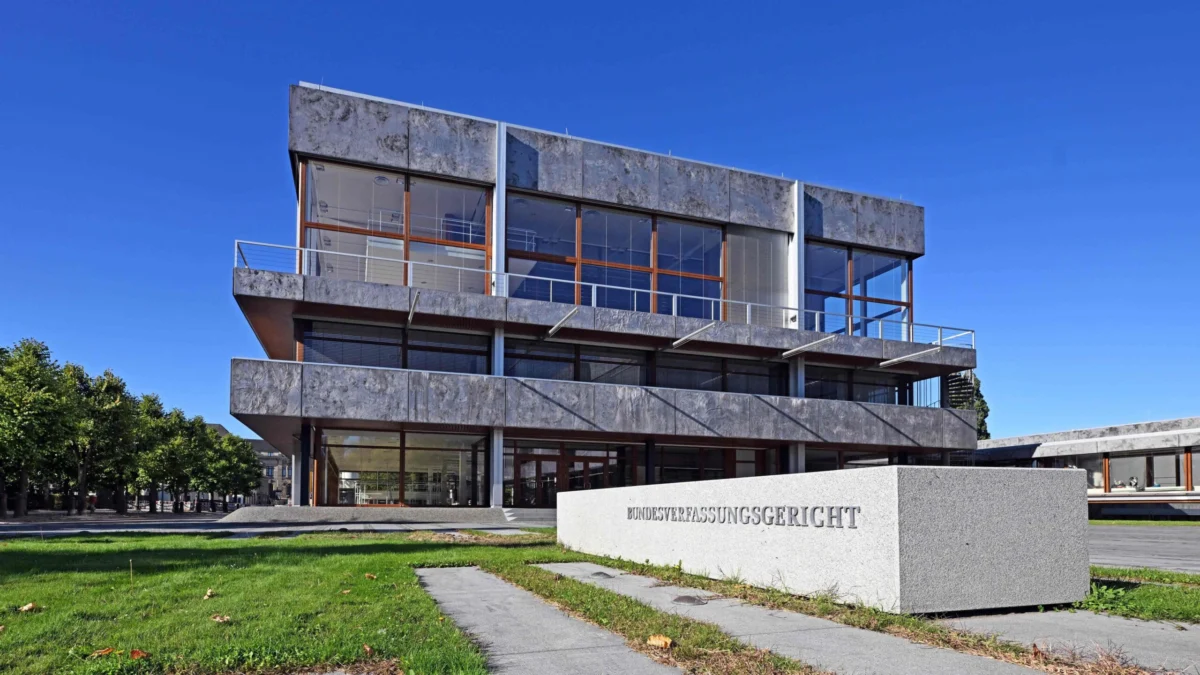
The German Federal Constitutional Court is currently at the center of a pivotal legal and political debate concerning the taxation of business assets upon inheritance. As the court deliberates, the complex interplay between tax law, economic policy, and social equity is coming into sharp focus. The implications of this decision extend far beyond individual family businesses, potentially reshaping the fiscal landscape for a significant portion of the German economy and impacting the financial stability of public services.
The Core of the Controversy: Privilege or Necessity?
At the heart of the legal challenge lies the question of whether and to what extent the state may grant preferential treatment to business assets compared to private assets under inheritance tax laws. This issue has ignited a fierce debate, with proponents arguing for the necessity of such provisions to safeguard the continuity of German family enterprises, preserve jobs, and maintain economic stability. Critics, however, contend that these exemptions create an uneven playing field, disproportionately benefiting the wealthy and undermining the principle of equal taxation.
Hamburg’s Finance Senator, Andreas Dressel, a prominent figure within the Social Democratic Party (SPD), has been vocal in quantifying the fiscal impact of these tax privileges. He reported that since the current regulations were introduced in July 2016, Hamburg alone has forgone an estimated 857 million euros in inheritance tax revenue. This figure represents approximately 7.5 percent of the nationwide volume of tax remissions related to business inheritances, indicating that the Hanseatic city is disproportionately affected. This substantial sum underscores the financial implications for regional budgets and the broader public good.
The legal proceedings were initiated by an individual who inherited a securities portfolio and real estate from his aunt. He was assessed approximately 50,000 euros in inheritance tax and argues that he is disadvantaged compared to those inheriting company assets. His claim rests on the fundamental principle of equal treatment enshrined in the German Basic Law (Grundgesetz).
A Decade of Legal and Political Scrutiny
The current legal framework for inheritance tax on business assets has its roots in a landmark ruling by the Federal Constitutional Court in December 2014. At that time, the court acknowledged that business assets could, in principle, be granted preferential treatment. The rationale behind this was to prevent the forced sale of businesses to cover inheritance tax liabilities, thereby protecting jobs and ensuring the long-term viability of companies.
However, the court also signaled that the extent of these exemptions needed careful consideration. The core of the subsequent legislative reforms, enacted in July 2016, introduced the "verschonungsbedarfsprüfung," or exemption requirement test. This test allows heirs to inherit business assets entirely tax-free, provided they demonstrate that their own financial resources are insufficient to cover the inheritance tax. Crucially, this provision initially had no upper limit, leading to criticism that it could be exploited through elaborate financial planning.
The controversy intensified with allegations that individuals could strategically "impoverish" themselves on paper to qualify for these exemptions, for instance, by transferring existing assets into closed private foundations prior to an inheritance. This practice, critics argue, allows for the accumulation of significant wealth across generations with minimal or no tax burden, starkly contrasting with the tax obligations faced by individuals inheriting only private assets.
The "Armrechnen" Controversy: A Loophole Exploited?
Kevin Kühnert, a former SPD General Secretary and now active with the Bürgerbewegung Finanzwende (Citizens’ Movement for Financial Transition), has been a vocal critic of the current system. Speaking in Karlsruhe, he characterized the exemption requirement test as an invitation to "armrechnen" – a deliberate process of making oneself appear poor for tax purposes. Kühnert argues that the law has shifted its focus from protecting essential business functions and jobs to merely assessing the liquidity of the inheritor. If an inheritor can demonstrate a lack of personal funds to pay the tax, even if this situation was engineered, the tax liability can be completely waived. This perceived loophole has fueled public discontent and calls for reform.

Independent experts have corroborated the potential for substantial tax exemptions. Professor Swen Bäuml, a tax law specialist, explained that individuals who properly structure their assets can, by law, transfer multi-billion euro business assets tax-free. He noted that the key is the ratio of management assets to the total value of the business. If this ratio is low, substantial exemptions are possible.
Industry’s Defense: Protecting Economic Foundations
Representatives from the business and industrial sectors have strongly defended the existing privileges, arguing that they are essential for the survival and competitiveness of German companies. Rainer Kirchdörfer, a board member of the Stiftung Familienunternehmen (Foundation of Family Businesses), countered the figures presented by tax authorities, stating that business assets are not liquid cash in a bank account but are tied up in machinery, patents, and buildings. Liquidating these assets to pay inheritance tax would cripple the business and lead to job losses.

Monika Wünnemann from the Federation of German Industries (BDI) expressed concerns about the potential negative consequences of altering the current regulations. She asserted that the differences in taxation between business and private assets are "objectively justified." Wünnemann argued that inheritance tax on businesses should ideally be paid from profit distributions, a process that she believes would weaken investment capacity.
The Contentious Issue of Residential Property
A particularly contentious area of debate involves the tax treatment of inherited residential properties, especially for large housing companies. The plaintiff in the current case highlights the disparity: while three inherited apartments might be subject to taxation, an inheritance of 300 apartments could be entirely tax-exempt.

The Federal Constitutional Court’s previous rulings have addressed this specific aspect. In a 2017 decision, the Federal Fiscal Court (Bundesfinanzhof) rejected the "300-unit rule" as an arbitrary benchmark. The court stated that the mere number of properties was not the decisive factor. Instead, the crucial element was whether the company provided services beyond standard rental and property management, such as cleaning, security, or hotel-like services. If a company’s primary activity is simply collecting rent, regardless of the number of properties, it is considered to be managing assets, not operating a business in a way that warrants tax exemption.
However, the practical application of these legal principles has been subject to political intervention. In 2018, the finance ministries of the federal states issued a non-application decree (Nichtanwendungserlass), instructing their tax authorities to continue adhering to the 300-unit threshold, effectively overriding the Federal Fiscal Court’s ruling. This administrative measure has been a significant point of contention, suggesting a political desire to maintain the status quo for large real estate companies.
The Political Stakes and Potential Ramifications

The ongoing legal battle is taking place against a backdrop of significant political challenges for the ruling coalition parties, the CDU/CSU (Union) and the SPD. Both parties are reportedly facing internal divisions on the issue, reflecting the broader societal debate about wealth distribution and tax fairness. The outcome of the Constitutional Court’s decision could have far-reaching implications for these parties, potentially exacerbating existing tensions or offering a path towards a unified policy.
The court’s ruling is expected in several months. Regardless of the specific outcome, the proceedings have already underscored the deep-seated complexities and the considerable financial stakes involved in reforming Germany’s inheritance tax laws for business assets. The decision will not only impact the heirs of family businesses and large corporations but will also influence the state’s revenue streams, potentially affecting funding for public services, infrastructure, and social programs across Germany. The court’s deliberation is a critical juncture, tasked with balancing the need to preserve Germany’s economic backbone with the fundamental principle of equitable taxation for all citizens.
